Key facts
| What the worked example measures | Direct contribution: agreed revenue less the specified direct costs, before business overheads, owner management pay and tax. |
|---|---|
| What the benchmark measures | ATO 2023-24 total-expense-to-turnover ratios for the stated industry; not a profit or salary measure. |
| What cash measures | Receipts and payments in the period. An invoiced amount is not proof that cash has arrived. |
Use AxiomBlue job records to review the fixed-price repaint
- Open the accepted AxiomBlue quote and repaint job. Review actual preparation/application time and paint costs, keeping the original fixed price distinct from an approved Professional hallway variation; extra hours reduce contribution without automatically raising revenue.
- Check the agreed revenue and direct costs against the worked example below, using the job reference to find missing entries or supporting supplier records. Apply the stated labour-cost basis; do not use the customer’s billable rate as an employee wage cost. Calculate the example/worksheet totals explicitly rather than assuming an incomplete record is the final result.
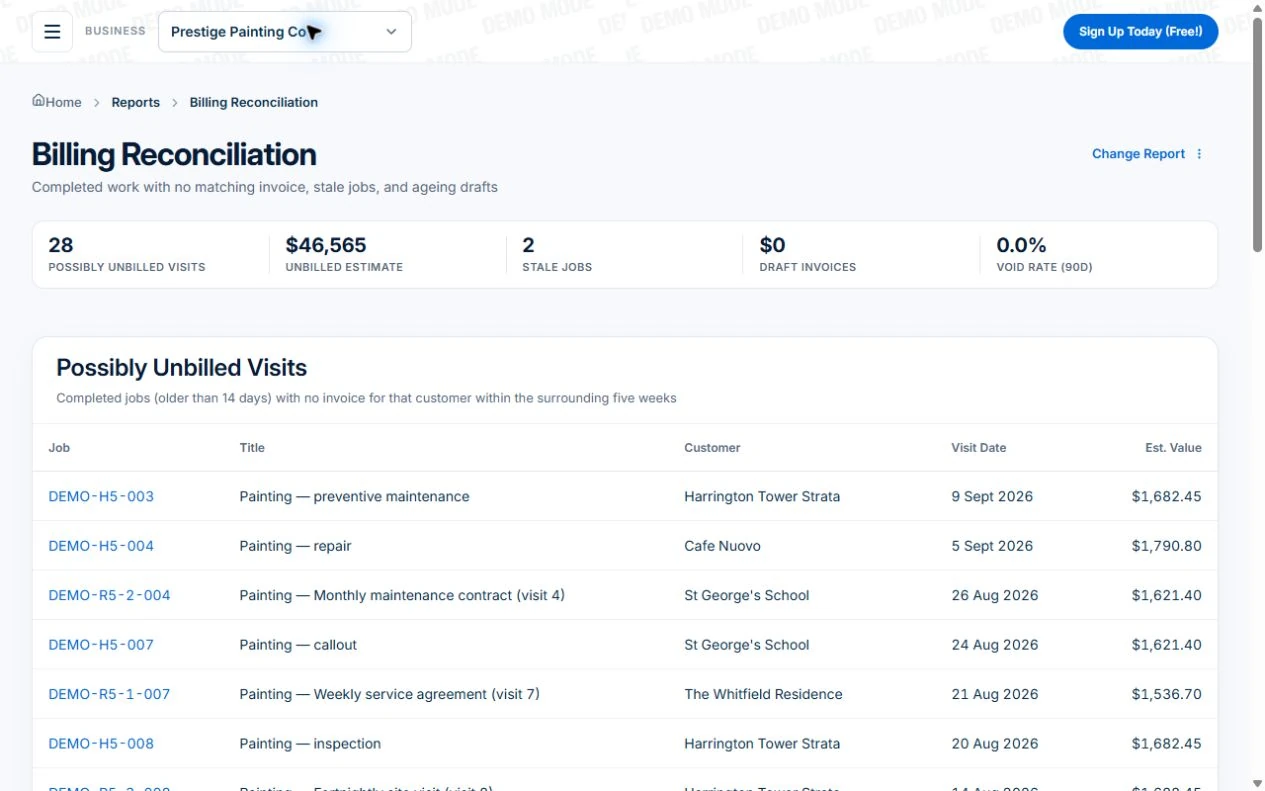
- Review the related invoice/claim and customer balance in AxiomBlue to distinguish billed value from payment. Use the resulting cost evidence to revise the next quote. Your accountant or accounting system supplies the wider overhead, net-profit, tax and owner-pay assessment; these job records do not produce that conclusion by themselves.
Check the work and the costs you are comparing
Cost preparation, access, coats, products, masking and cleanup explicitly. Compare the accepted scope with customer additions before treating extra work as billable.
Use the same scope and period on both sides of the comparison. Include the work needed to deliver the service, including travel, setup and return visits where relevant. Use actual current employment and supplier costs; the illustrative rates below are not award rates or recommended prices.
Read the ATO expense benchmark as expenses, not take-home profit
The ATO’s 2023-24 benchmark for painting services reports total expenses as a percentage of turnover, excluding GST. The average expense ratios are 43%, 63%, 80% for the turnover bands below. These are expense-to-turnover ratios, not net profit margins or owner salaries.
Scope matters: Labour and materials for painting buildings/structures; excludes mainly interior decorating and sign writing.
The ATO calculation subtracts payments to associated persons from total expenses. An owner’s drawings are also not the same as a delivery wage or a business expense. Subtracting a benchmark expense ratio from 100% does not show profit after paying an owner for all their work. Compare like-for-like records and budget owner delivery and management time separately.
Use the industry table to investigate differences, not to price an individual job. Businesses in different turnover bands are different populations; the table does not prove that growing your business will cause its margin to fall.
| Annual turnover, ex GST | Total expenses ÷ turnover range | Average total expenses ÷ turnover |
|---|---|---|
| $50,000 – $150,000 | 36% to 51% | 43% |
| $150,001 – $600,000 | 54% to 71% | 63% |
| More than $600,000 | 74% to 86% | 80% |
Sources: ATO: painting services benchmarks, 2023-24 · ATO: Benchmark ratio calculations
Worked example: a fixed-price repaint
Illustrative assumptions, all amounts excluding GST: An agreed $5,000 repaint; 50 planned paid hours at an assumed loaded cost of $45, plus $950 materials and other direct costs. Preparation takes ten extra paid hours.
The assumed delivery labour cost includes a budget allowance for the person doing the work, including owner delivery time where applicable. It is not a current legal pay minimum. Business overheads, owner management/admin time, finance costs and tax still need to be considered separately.
Planned direct contribution is $5,000 − $2,250 − $950 = $1,800 (36.0%). Actual direct contribution is $5,000 − $2,700 − $950 = $1,350 (27.0%). The $450 difference is the specified additional delivery cost; it is not an industry result or a claim about typical software savings.
Keep any approved extra revenue as a separate change to the calculation. For a fixed-price agreement, more recorded hours do not automatically increase the agreed price. If an invoice remains unpaid, the contribution calculation does not make it cash.
| Example measure | Planned | Actual |
|---|---|---|
| Agreed revenue | $5,000 | $5,000 |
| Specified delivery labour | $2,250 | $2,700 |
| Other specified direct costs | $950 | $950 |
| Direct contribution before overhead and other owner work | $1,800 / 36.0% | $1,350 / 27.0% |
Separate job contribution, business profit and owner pay
Job contribution helps identify underpriced scope or a delivery overrun. Business profit also depends on overheads and other costs across the period. Owner pay and drawings must be interpreted for your business structure; the amount left in the example is not a salary estimate.
Use a cost rate that reflects what delivery actually costs your business. Mark missing time or material records before relying on a job margin. If a job cost view excludes an expense, allow for it in the wider business review rather than treating the displayed margin as net profit.
Keep the records needed for the next pricing decision
In AxiomBlue, keep job time, materials and the agreed price together so you can review delivery and billing. Free supports a limited one-user core workflow; Basic adds capacity and photo/document uploads.
Professional is required for recurring job series, variation approvals, weekly timesheets, business reports and workflow automation. Inspect the relevant records in the demo or on the required plan. A job cost view does not replace a profit and loss statement, payroll or bank reconciliation.
Check completed work against invoices and receipts. Record agreed scope changes before including them in revenue, and review work already billed before preparing another invoice.
Use the review to change the next quote or contract
Look for a repeated cause: underestimated preparation, travel, a return visit, extra scope or missing cost records. Update the estimate and explain any revised price or exclusion before the next job is agreed.
Check a week or month that includes ordinary work and an exception. Review the underlying records with your bookkeeper or accountant when the job contribution and business accounts tell different stories. Check current employment, tax and contractual obligations against the relevant official guidance.
Common questions
Questions about painting profitability
Is a painting business profitable?
A painting business is profitable when its revenue covers delivery costs, overheads and an appropriate allowance for the owner’s work. Start with actual completed work and costs, then check whether the invoices have been paid.
Does an ATO expense ratio tell me my profit margin?
No. It compares specified tax-return expenses with turnover for a stated industry and year. Associated-person payments are removed from the ATO expense calculation. It does not establish net profit after owner pay, drawings or cash available to take home.
What does the worked example leave out?
The example identifies the specified direct costs and contribution. Business overheads, owner management/admin work, finance costs and tax remain outside it. Its rates are illustrative assumptions, not award rates or recommended customer prices.
Can a profitable job still cause a cash problem?
Yes. Work and costs can be recorded before the customer pays. Check invoices, receipts, supplier commitments and other outgoing payments alongside the contribution calculation.
Which AxiomBlue plan do the records need?
Free supports one user and limited core jobs, time and invoicing. Uploads start on Basic. Recurring series, variation approvals, weekly timesheets, reports and automations require Professional; inspect those in the demo or on the required plan.
Put it to work
Your practical checklist
- Select completed work and the matching agreed price.
- Check paid delivery time, materials, travel and missing records.
- Allow for overheads and the owner’s delivery and management work.
- Use the benchmark only if its industry and measure match your business.
- Reconcile invoices and receipts, then update the next estimate.
See the records in Axiom Blue
Try the workflow with a familiar job.
Features and usage limits vary by plan. Review the tools relevant to your process before choosing your setup.
Product instructions
Published by Axiom Blue. Applicable ATO expense benchmarks and their calculation method were checked on 6 October 2026. Worked examples use illustrative assumptions; their costs are not award rates or recommended prices. Check your own costs and current obligations.